Foreign Founders: Skip the Company Seal in Singapore and Sign Remotely

Ray Tay
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
Published: 11 November 2025 · Last reviewed: 5 December 2025 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
 2 January, 2025
 2 January, 2025
What does “Indonesia reduces minimum paid-up capital” mean for foreign investors?
It means that the minimum investment required to establish a foreign-owned company (PT PMA) has been lowered from IDR 10 billion to IDR 2.5 billion, making market entry more accessible for SMEs and startups.
How does the new regulation affect Singapore-based businesses?
Singaporean companies can now expand into Indonesia with lower financial commitments, leveraging the proximity and strong bilateral ties between both economies for easier cross-border collaboration.
Are there specific sectors that benefit most from this change?
Yes. Sectors such as digital technology, healthcare, renewable energy, and consumer goods stand to gain significantly due to lower entry costs and high domestic demand.
Does lowering paid-up capital affect compliance or legal obligations?
No. While the entry barrier is lower, companies must still comply with Indonesia’s investment regulations by including OSS-RBA registration, tax reporting, and periodic investment activity reports (LKPM).
What new business opportunities arise from Indonesia’s lower paid-up capital rule?
The reform opens doors for small and medium foreign investors to participate in Indonesia’s growth industries, particularly in tech startups, green energy, e-commerce, and logistics. It also enables regional firms to establish local subsidiaries faster, test new markets, and scale operations without heavy upfront costs.
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
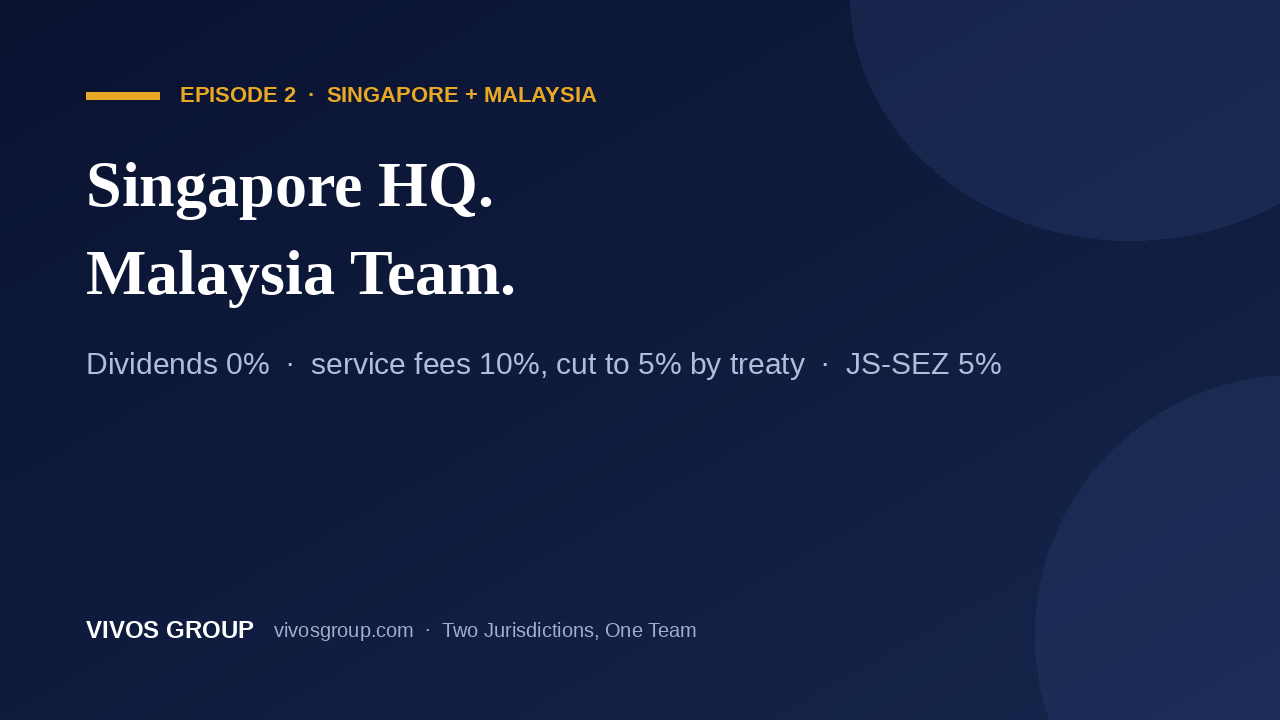
What the Singapore parent of a Malaysian Sdn. Bhd. must get right in 2026: tax-exempt Malaysian dividends under section 13(8), invoicing and 5% treaty withholding,…