Paying Your Hong Kong Sister Company from Singapore: The Withholding Tax Checklist

Ray Tay
A Singapore company paying its Hong Kong sister company must withhold 15% on interest and 10% on royalties, and file and pay that tax to…
Published: 7 October 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
If your Singapore company is not GST-registered, you issue a commercial invoice with no GST shown. If you are GST-registered, you must issue a tax invoice/basics-of-gst/invoicing-price-display-and-record-keeping/invoicing-customers) within 30 days showing the words “Tax Invoice,” your GST registration number, the 9% GST rate as of 2026, and the GST amount. On top of that, InvoiceNow e-invoicing is being phased in across GST-registered businesses, with mandatory cohorts rolling out through April 2031 as per IRAS.
TL;DR:
- Companies are required to issue a tax invoice within 30 days if they are GST-registered, including the words “Tax Invoice,” GST registration number, and GST details.
- A full tax invoice lists specific fields like invoice number, date, description, quantities, prices, and GST amounts, while a simplified invoice is allowed for totals under S$1,000.
- Zero-rated exports need proof of export within 60 days; otherwise, the transaction must be taxed at 9% and marked as “GST 0%”.
- InvoiceNow mandatory participation phases in from November 2025 to April 2031, with early connection enabling faster refunds and cleaner data.
- Proper record keeping, including five-year retention of invoices and supporting documents, is essential for compliance and smoother IRAS audits.
The fields you need depend entirely on whether you charge GST. IRAS requires a full tax invoice from GST-registered suppliers for standard-rated supplies to other GST-registered businesses. That invoice must carry:
A simplified tax invoice is permitted when the total payable, GST included, does not exceed S$1,000. We cover the simplified format in detail in the next section.
If your company is not GST-registered, none of the GST fields apply. You issue a commercial invoice instead: business name and address, invoice number and date, description of goods or services, quantity, unit price, and total amount due. Never show a GST registration number or a GST amount on a commercial invoice. Many foreign founders inherit invoice templates from their home country that include a VAT or tax ID line by default, and leaving that field populated or mislabeled on a Singapore invoice creates confusion for overseas clients trying to reconcile their own tax filings, and can misrepresent your company’s registration status.
Where invoices are issued in a foreign currency, the GST amount itself must still be convertible to Singapore dollars using a consistent exchange rate, applied the same way invoice after invoice rather than switched between sources.
You charge GST only once your company is GST-registered, and only on standard-rated supplies made to customers in Singapore.
Timing matters as much as the rate. According to IRAS’s GST General Guide, a tax invoice must be issued within 30 days from the time of supply, which is generally the earlier of the date goods are delivered or services performed, or the date payment is received. Missing that window does not cancel your GST liability, but it does create a compliance gap if IRAS reviews your records.
A few situations change what you need to issue:
When the total amount payable, GST included, is S$1,000 or less, you can skip the full tax invoice and issue a simplified version instead. A simplified tax invoice needs fewer fields but still has to function as valid GST documentation.
Receipts can stand in for an invoice in some retail and point-of-sale contexts, provided they carry:
This format works well for retail counters, cafés, and low-value business-to-business sales where issuing a full nine-field tax invoice for a small purchase would be disproportionate. It does not replace the full tax invoice requirement once a GST-registered customer requests one for their own input tax claim.
Foreign founders running a Singapore company that bills overseas clients deal with zero-rating constantly, and it is one of the areas IRAS scrutinizes most closely during audits.
To substantiate a zero-rated export, IRAS requires documentary evidence tying the sale to an actual export out of Singapore:
A critical deadline sits inside this rule: if the goods are not exported within 60 days of the time of supply, the transaction must be standard-rated and GST accounted for at 9%, even if you originally invoiced at 0%. If you do issue a tax invoice for a zero-rated supply, mark the line clearly as “GST 0%” rather than leaving the GST field blank, which avoids ambiguity if the invoice is ever reviewed.
Pro Tip: Build a export-document folder per invoice number from day one, not retroactively. Reconstructing shipping evidence months later for an IRAS query is far harder than filing it as each shipment goes out.
InvoiceNow is Singapore’s nationwide e-invoicing network, and GST-registered businesses are being brought onto it in stages rather than all at once. According to IRAS’s GST InvoiceNow Requirement page, mandatory participation is tied to your registration date and the scale of your business, with cohorts phased in from 1 November 2025, 1 April 2026, and then annually from April 2028 through April 2031.
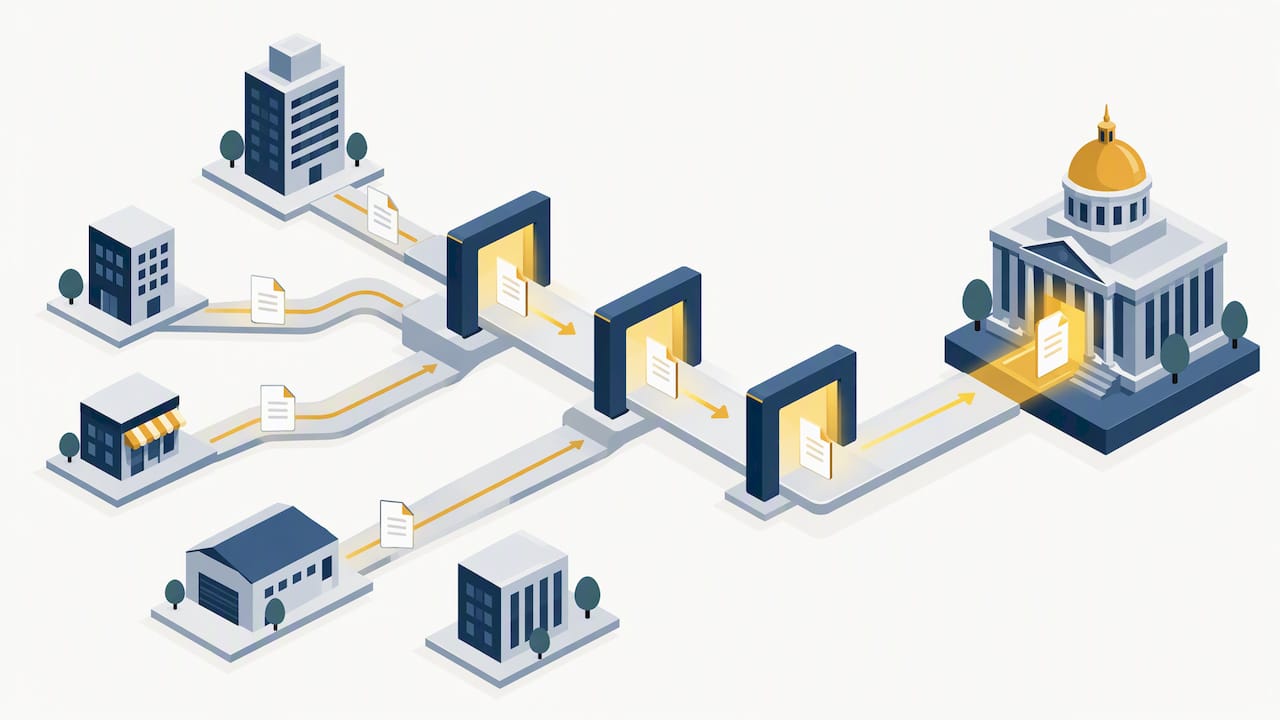
The extension confirmed at Committee of Supply 2026 brings every GST-registered business onto InvoiceNow by April 2031. That timetable gives founders incorporating a new Singapore company now a reasonable window to build e-invoicing into their accounting setup from the start, rather than retrofitting it later.
Once a cohort date applies to you, the scope covers more than sales invoices:
Certain registrants fall outside the mandate, including some overseas entities and businesses registered solely under reverse-charge rules. For everyone else, the submission deadline follows whichever comes first: the date you file your GST return, or the statutory due date for that return.
The practical upside is real. IRAS and IMDA frame mandatory submission as a way to shorten GST audit cycles and speed up refund processing, since invoice data reaches IRAS automatically rather than through a manual request during a review.
Getting InvoiceNow-ready is a systems task, not a form to fill in. IMDA’s technical playbook lays out the mechanics, and most of the work happens inside your accounting software rather than on paper.
Pro Tip: If you run an online storefront alongside invoiced B2B sales, map how your point-of-sale or e-commerce platform exports transaction data before your InvoiceNow cohort date arrives; a Shopify setup guide for Singapore merchants is a useful reference for aligning checkout data with your accounting feed.
We go deeper on the implementation side, including common connection pitfalls, in our guide to e-invoicing in Singapore.
GST invoices and the documents behind them need to survive longer than most founders expect. IRAS requires that invoices and supporting records be kept for at least 5 years, and Singapore Customs applies the same retention period to trade documents tied to imports and exports.
| What to retain | Why it matters |
|---|---|
| Tax invoices and commercial invoices | Primary evidence of the transaction and GST treatment |
| Export permits, airway bills, bills of lading | Substantiates zero-rated export claims |
| Packing lists and proof of payment | Confirms goods and payment match the invoice |
| Credit notes and debit notes | Shows adjustments were properly recorded |
Electronic storage is acceptable, which removes the need for a physical filing cabinet, but only if the records stay retrievable and legible for the full retention period.
Our bookkeeping and compliance service sets this indexing up from month one, so records are audit-ready without a scramble when IRAS sends a query.
Founders incorporating from overseas tend to build invoicing processes in the wrong order, often designing templates before deciding on GST registration timing. This sequence avoids the rework.
We incorporate Singapore companies for foreign founders, handling nominee resident director, registered address, corporate secretary, GST registration, and bookkeeping, and we offer setup support in multiple jurisdictions for founders expanding their businesses.
Most GST issues IRAS flags trace back to a small set of recurring errors, and almost all of them are cheaper to fix now than during a review.
Penalties for incorrect GST returns can include financial penalties and back-tax assessments, and IRAS operates a Voluntary Disclosure Programme that reduces penalties for businesses that correct errors before IRAS detects them independently.
Pro Tip: Run a quarterly self-check against your own invoice checklist, comparing a sample of invoices against the mandatory field list, rather than waiting for your annual filing to surface problems.
InvoiceNow is often framed purely as a compliance deadline, but businesses that connect early get cleaner data, faster GST refunds, and fewer manual corrections at filing time.
We set up new Singapore companies for foreign founders, covering nominee resident director, registered address, corporate secretary, GST registration, and bookkeeping, with similar services available in other jurisdictions. Our recommendation is to connect to InvoiceNow as part of your initial accounting setup, not as a separate project once your cohort date is already close.
Getting invoice templates, GST registration timing, and InvoiceNow onboarding right at the same time is harder for a founder managing it alone from overseas than for a team that does this setup daily. We handle foreign-founder and local incorporation, corporate secretary duties, GST registration and filing, bookkeeping and compliance, and ongoing accounting, so your invoicing process is built correctly before your first GST return is due rather than patched together afterward. We also provide nominee resident director, registered address, corporate secretary, GST registration, and bookkeeping support for founders expanding in multiple jurisdictions. Check our pricing and packages to see what fits your stage, or review our GST registration and filing support if your registration date is approaching.
A Singapore invoice needs your business name and address, an invoice number and date, a description of goods or services, quantity, and the total amount due. If you are GST-registered, additional fields apply, including “Tax Invoice,” your GST number, the GST rate, and the GST amount.
At minimum, every invoice needs a business name, address, invoice number, date, description of the supply, and total amount payable. A GST-registered business must also add the words “Tax Invoice,” its GST registration number, the GST rate of 9%, and the GST amount shown separately, as set out in IRAS’s invoicing guidance.
Yes, if your company is not GST-registered you issue a commercial invoice with no GST shown at all, and you never display a GST registration number or GST amount. Once you register for GST, you switch to issuing tax invoices that include the GST rate and amount on standard-rated supplies.
Individuals operating as sole proprietors or self-employed persons can issue invoices, and the same GST rules apply based on registration status. A sole proprietor who crosses the GST registration threshold must issue tax invoices exactly like a company, following the same field requirements IRAS sets for registered businesses.
 2 January, 2025
 2 January, 2025
A Singapore company paying its Hong Kong sister company must withhold 15% on interest and 10% on royalties, and file and pay that tax to…
Practitioner checklist for founders transferring shares in Singapore: compute 0.2% stamp duty, meet the 14 or 30 day deadlines, secure board approval, and...