Singapore Certificate of Residence: Rules and Application Steps
Published: 26 August 2026 · Last reviewed: 9 October 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
Quick answer: A Singapore Certificate of Residence (COR) is a letter from IRAS certifying that a company is a Singapore tax resident, so it can claim benefits under Singapore’s double tax agreements (DTAs). A company qualifies when the control and management of its business, usually the board’s strategic decisions, is exercised in Singapore. It applies online at myTax Portal for the current calendar year, up to 4 back years, or 1 advance year from October; IRAS processes applications within 7 working days and posts a digital copy to myTax Portal. Foreign-owned investment holding companies with only passive or foreign-sourced income, nominee companies and companies incorporated outside Singapore are generally not eligible.
Singapore Certificate of Residence at a glance
| Item | Rule |
|---|---|
| What it is | An IRAS letter certifying Singapore tax residency, used to claim DTA benefits abroad |
| Residency test | Control and management of the business exercised in Singapore, usually where the board makes strategic decisions |
| How to apply | Online at myTax Portal (mytax.iras.gov.sg), except in specific circumstances |
| Years you can apply for | Current calendar year, up to 4 back years, and 1 advance year from October of the current year |
| Processing time | Within 7 working days of IRAS receiving the application |
| How you receive it | Digital copy under View Notices/Letters on myTax Portal; paper copy within 4 working days if the company is on paper notices |
| Generally not eligible | Foreign-owned investment holding companies with purely passive or foreign-sourced income, nominee companies, and non-Singapore-incorporated companies |
A foreign-owned investment holding company can still obtain a COR if it shows that control and management is exercised in Singapore and that it has a genuine commercial reason to be here, for example at least one Singapore-based executive director who is not a nominee, at least one key employee such as the CEO, CFO or COO based in Singapore, or management by a related company in Singapore.
Sources: IRAS, Applying for a Certificate of Residence and IRAS, Tax Residency of a Company, checked 9 October 2026.
A Certificate of Residence (COR) is an official letter the Inland Revenue Authority of Singapore (IRAS) issues to confirm tax residency. Companies and individuals use it to claim relief under Singapore’s extensive network of double tax agreements, avoiding the same income being taxed twice.
- Issued exclusively by IRAS, no other body can certify residency
- Needed mainly by companies earning foreign income who want treaty relief
- Individuals need one in specific cases, such as claiming relief on foreign employment income
Key Takeaways
A valid Certificate of Residence depends on demonstrable control and management in Singapore, not just incorporation status or a mailing address.
| Point | Details |
|---|---|
| Self-check residency first | Confirm board meetings and strategic decisions genuinely happen in Singapore before applying. |
| Prepare documentary evidence | Gather board minutes, attendance records, payroll, and office lease documents in advance. |
| Apply through myTax | Submit via Singpass login, selecting the correct calendar year, and expect 2 to 3 weeks processing. |
| Watch the claim window | File treaty claims before relief applies or within two calendar years of receiving the COR. |
| Build substance with VIVOS | VIVOS’s incorporation and corporate secretarial services help structure board governance from day one. |
Table of Contents
- Does My Company Qualify as a Singapore Tax Resident?
- How Do I Get a Tax Residency Certificate in Singapore?
- Resident vs Non-Resident Company Tax Treatment
- Why COR Applications Get Rejected
- Tax Reclaim Forms and Treaty Claim Deadlines
- What This 2026 Guidance Actually Changes for Applicants
- Get Board Governance Right From Incorporation
- Sources
Does My Company Qualify as a Singapore Tax Resident?
IRAS applies the control-and-management test: a company is tax resident in Singapore when the strategic decisions of the business are made here, typically through board meetings. This isn’t about where the company is incorporated or where it banks. It’s about where the people steering the ship actually sit when they make the calls that matter, and residency gets assessed fresh every year.
IRAS looks for a specific pattern of evidence before granting a COR:
- Physical board meetings held in Singapore, with directors present and minutes on file
- Genuine local decision-making, not administrative rubber-stamping of decisions made elsewhere
- Local executives or staff with real authority over operations
- A physical office presence and payroll records tied to Singapore
Several setups routinely fail this test. A board made up entirely of nominee directors with no say in strategy is a common red flag. So is a company incorporated outside Singapore trying to claim residency without shifting any real decision-making here. Passive holding companies with no local executive presence face extra scrutiny too.
The rules on virtual meetings have tightened. EY’s analysis of the updated guidance notes that for a hybrid or virtual board meeting to count toward Singapore residency, either at least half the directors with real authority must be physically present in Singapore, or the chairman must be. A screen full of faces logging in from five countries doesn’t cut it anymore.
Pro Tip: Don’t wait until your COR application to think about board attendance. Build a habit of scheduling at least one substantive board meeting in Singapore each quarter, and keep dated minutes as a running record.
How Do I Get a Tax Residency Certificate in Singapore?
Most companies and individuals apply through the myTax portal, IRAS’s online filing system. Paper forms remain an option for a small number of cases where digital access isn’t possible, but myTax is the default route and the faster one.
The application follows a set sequence:
- Log in to myTax using Singpass (or Singpass Foreign user Account for foreign individuals)
- Navigate to the Certificate of Residence application function
- Select the calendar year or years you need the certificate for
- Upload supporting documents, such as board minutes or financial statements, where requested
- Submit the application and note your reference number for follow-up
You can apply for the current calendar year and up to four prior years in a single COR request, which matters if you’re catching up on treaty claims from an earlier financial year. There’s a catch worth flagging early: treaty benefits generally need to be claimed either before the relief is applied or within a limited period after receiving the COR. Miss that window and you may lose the relief entirely, even with a valid certificate in hand.
IRAS’s stated processing time for COR applications is 2 to 3 weeks as of 2026. Build that lead time into any deadline you’re working against with a foreign tax authority, particularly if a treaty claim has its own filing cutoff.
Resident vs Non-Resident Company Tax Treatment
A COR only matters because residency status changes what a company can actually claim, especially given why Singapore has no capital gains tax and the resulting treaty implications. The table below reflects treatment as of 2026, though every figure is subject to per-treaty variation.
| Treatment Aspect | Singapore Tax Resident | Non-Resident Company |
|---|---|---|
| DTA relief eligibility | Can claim relief under applicable DTAs with a valid COR | Not eligible for DTA relief on Singapore-sourced treaty claims |
| Withholding tax on foreign dividends | May qualify for reduced treaty rates | Generally faces standard, non-treaty withholding rates abroad |
| Foreign-sourced income exemption | Can access exemptions under Singapore’s foreign income rules | Exemptions generally unavailable without residency status |
| Tax reclaim form submission | Can submit reclaim forms to foreign tax authorities via IRAS certification | Cannot certify residency, so reclaim forms are typically rejected |
As PwC’s summary of Singapore’s corporate residence rules points out, residence turns on where control and management sit, not on whether the company has a permanent establishment here. That distinction trips up a lot of foreign-owned entities that assume having an office automatically means having residency.
Why COR Applications Get Rejected
The most common cause of rejection isn’t a paperwork error. It’s a governance structure that can’t demonstrate real decision-making inside Singapore. A board stacked with nominee directors who never weigh in on strategy, or minutes that read like they were drafted after the fact to match a template, both raise flags with IRAS reviewers.
Documents that strengthen an application include:
- Signed board minutes showing substantive discussion, not just formal resolutions
- Director attendance records tied to specific meeting dates and locations
- Employment and payroll records for local staff
- A registered office lease and an organizational chart showing reporting lines
- Records of meeting logistics, including travel for directors based overseas
For foreign-owned investment holding companies specifically, EY’s advisory notes that IRAS now places extra weight on local executive presence or management delegated to a related Singapore entity, rather than accepting a purely nominal local footprint.
Setting this up correctly from day one is far easier than fixing it retroactively. VIVOS’s Singapore incorporation service helps new companies structure board governance properly at formation, and VIVOS’s corporate secretarial services keep minutes, resolutions, and attendance records audit-ready on an ongoing basis.
Pro Tip: Ask your corporate secretary to flag any board meeting where fewer than half the directors attend in person. That’s exactly the pattern IRAS reviewers look for when they suspect a rubber-stamp board.
Tax Reclaim Forms and Treaty Claim Deadlines
A COR alone doesn’t always finish the job. Some treaty partners require a specific tax reclaim form, certified by IRAS, before they’ll process relief. Others accept the COR as standalone proof. Which applies depends entirely on the treaty in question, so check the list of Singapore’s DTAs for the counterparty jurisdiction before assuming one route works everywhere.
Once you have a COR in hand, the practical next steps are:
- Confirm with the foreign tax authority whether a reclaim form needs IRAS certification alongside the COR
- Submit both documents within the treaty’s claim window, generally before relief is applied or within two calendar years of the COR
- Keep copies of everything submitted, since foreign tax authorities can audit claims years after the fact
Treat the COR as the start of a paper trail, not the end of one. Foreign tax authorities that grant relief today can and do ask for supporting evidence later.
What This 2026 Guidance Actually Changes for Applicants
Most advice on COR applications still treats the process as a paperwork exercise: fill in the myTax fields, attach a few documents, wait three weeks. That undersells what IRAS is actually testing. The tightened stance on hybrid and virtual board meetings signals a broader shift toward verifying substance rather than accepting form. A company can incorporate perfectly, hold quarterly Zoom calls with a majority-overseas board, and still fail the control-and-management test if the people with real authority aren’t physically here often enough.
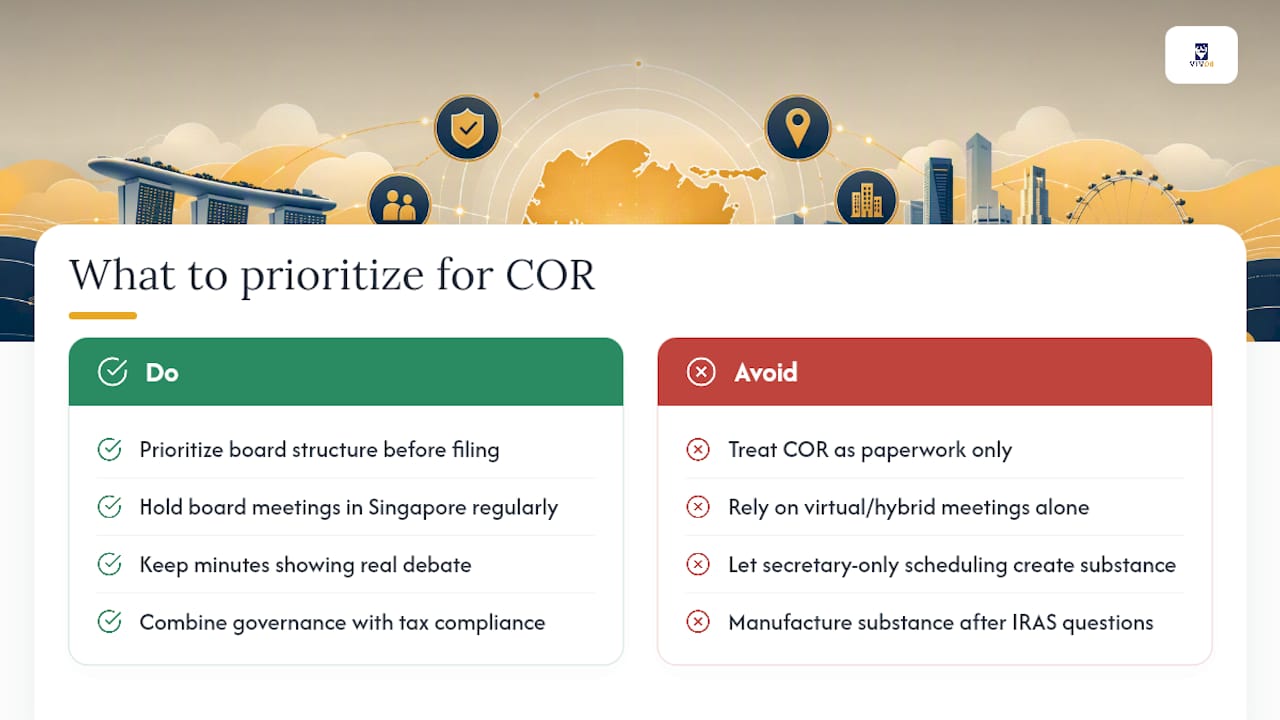
Where conventional advice falls short is treating governance and tax compliance as separate workstreams. They aren’t. A board that meets in Singapore because a corporate secretary scheduled it there, with minutes that reflect actual debate rather than pre-agreed resolutions, is doing double duty: satisfying company law and building the exact evidence IRAS wants for residency.
If you’re setting up now, prioritize the board structure before the tax filing. Getting a COR later is straightforward once the substance already exists. Manufacturing that substance after IRAS raises questions is the hard, expensive way to learn this lesson.
— Ray
Get Board Governance Right From Incorporation
VIVOS handles the governance work that makes a Certificate of Residence application straightforward instead of stressful. For companies setting up in Singapore or already operating here, VIVOS’s incorporation service structures your board and local presence correctly from day one, and VIVOS’s corporate secretarial services maintain the minutes, attendance records, and resolutions IRAS reviewers actually look for.
Companies that need ongoing tax filing support after securing residency can also turn to VIVOS’s corporate tax filing services to keep annual submissions aligned with their COR status. If your board is scattered across time zones and you’re unsure whether your current setup would pass IRAS scrutiny, reach out to VIVOS for a review of your governance structure and next steps toward incorporation or corporate secretarial support.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Apply for Certificate of Residence (COR) — IRAS
- Tax residency of a company: new guidance for virtual meetings and revised considerations — EY (Singapore) (PDF)
- Singapore — Corporate residence — PwC Tax Summaries
Recommended
- Singapore Global Investor Programme (GIP) 2026 PR Guide | VIVOS
- Singapore EntrePass 2026: Eligibility & Renewal Guide | VIVOS
- EntrePass Singapore: Eligibility, Business Plan & Compliance Tips
- How Can You Secure Singapore Residency Through Business?
Related guides
Most Popular
 2 January, 2025
Why Singapore Comes Into Action For Chinese Companies
 2 January, 2025
Malaysia’s Budget 2025: What The Dividend Tax Means For You
Frequently
Asked Questions
-
What is a Certificate of Residence in Singapore?
A Certificate of Residence (COR) is a letter issued by IRAS certifying that a company is a Singapore tax resident. Foreign tax authorities generally ask for it before granting benefits under a double tax agreement (DTA) with Singapore, such as reduced withholding tax.
-
How do I apply for a Certificate of Residence?
Apply online at myTax Portal (mytax.iras.gov.sg). A company can apply for the current calendar year, up to 4 back calendar years, and 1 advance calendar year from October of the current year. Only specific circumstances, such as a COR for a sole proprietorship or partnership owned by the company, require a written application.
-
How long does IRAS take to issue a Certificate of Residence?
IRAS processes a COR application within 7 working days of receiving it. The approved COR is then available as a digital copy under View Notices/Letters on myTax Portal; companies on email notifications are told within 1 to 3 working days, and companies on paper notices receive the paper COR within 4 working days.
-
Does my company qualify as a Singapore tax resident?
A company is a Singapore tax resident for a Year of Assessment if the control and management of its business was exercised in Singapore in the preceding calendar year. Control and management means strategic decision-making, usually shown by where the board of directors meets and makes those decisions.
-
Can a foreign-owned holding company get a Certificate of Residence?
Generally not, if it is a foreign-owned investment holding company with purely passive or foreign-sourced income. IRAS may still issue a COR if the company shows that control and management is exercised in Singapore and that it has a genuine commercial reason to be here, for example a Singapore-based executive director who is not a nominee, a key employee such as the CEO, CFO or COO based in Singapore, or management by a related Singapore company. Nominee companies and companies incorporated outside Singapore are generally not eligible.
Recents Blogs

Nominee Director Services in Singapore: 7 Providers Ranked on 6 Checks (2026)

Since 9 June 2025, a nominee director acting by way of business in Singapore must be arranged by an ACRA-registered corporate service provider.
Does Singapore Offer Citizenship by Investment? (2026)
Singapore has no citizenship by investment programme. Investors can get PR through the Global Investor Programme, then apply to ICA for citizenship after at least…