Foreign Founders: Skip the Company Seal in Singapore and Sign Remotely

Ray Tay
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
Published: 18 September 2026 · Last reviewed: 30 September 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
Quick answer: Singapore is one of the world’s most established hubs for international trading companies — physical commodities, brokering, and cross-border distribution — thanks to its port location, extensive free trade agreement network, and the Global Trader Programme (GTP), which offers a concessionary tax rate of 5%, 10% or 15% on qualifying trading income for five years, against the standard 17% corporate tax rate. GTP has just been extended to 2031, with Environmental Attribute Certificates (EACs) added as qualifying “green” products from 13 February 2026. Incorporation takes 1-3 days; GTP approval is a separate application to Enterprise Singapore, assessed on trading volume, track record, and substance in Singapore.
TL;DR:
- A standard Pte Ltd can trade internationally from day one — no special licence is needed just to buy and sell goods across borders.
- The Global Trader Programme (GTP) is the incentive that makes Singapore genuinely competitive for trading companies: 5-15% tax on qualifying income vs the standard 17% rate, for five years.
- GTP has been extended to 2031, and Environmental Attribute Certificates (EACs) — carbon credits and similar instruments — became qualifying “green and sustainable products” from 13 February 2026.
- GTP is not automatic — Enterprise Singapore assesses your trading track record, volume, and the substantive functions (strategic management, risk management, logistics) you commit to running from Singapore, not just a mailbox.
- Most new trading companies incorporate and start operating on standard tax rates first, then apply for GTP once they have a track record Enterprise Singapore will actually credit.
- VIVOS incorporates the entity and structures it for a future GTP application; the GTP application itself is a substance-heavy submission normally built with a tax advisor once real trading volume exists.
| Factor | Standard Pte Ltd | Under GTP |
|---|---|---|
| Corporate tax rate on qualifying trading income | 17% | 5%, 10%, or 15% (tier depends on your award) |
| Duration | N/A | 5 years per award, renewable subject to review |
| Qualifying income | N/A | Physical trading, brokering of physical trades, derivative trading, and qualifying commodities/goods — now including Environmental Attribute Certificates from 13 Feb 2026 |
| Administered by | N/A | Enterprise Singapore |
| Programme horizon | N/A | Extended to 2031 |
The February 2026 update matters specifically for commodity and energy trading houses: Environmental Attribute Certificates — carbon credits and similar tradeable environmental instruments — now count as qualifying “green and sustainable products” under GTP, opening the incentive to a category of trading activity that has grown rapidly but previously sat in a grey area for the programme.
GTP is not granted at incorporation — it is a separate award assessed on substance and track record. Enterprise Singapore generally expects:
Because of this substance bar, most new trading companies incorporate and operate on standard tax rates first, build a genuine Singapore-based track record, and apply for GTP once there is real trading volume and local substance to point to — applying too early with no history is a common way to get a weaker outcome or rejection.
“We get the Pte Ltd incorporated, the company secretary and accounting set up properly, and the entity structured so it is ready for a GTP application once you have the trading volume and substance to support one,” says Ray Tay, Co-Founder and Managing Director of VIVOS. “What we do not do is file the GTP application itself — that is a substance-heavy submission to Enterprise Singapore, normally built alongside a tax advisor once real trading history exists, and it is different work from company incorporation. We also do not arrange trade finance directly; that runs through your bank.”
VIVOS incorporates the Pte Ltd and keeps your company secretary and accounting compliant while you build the trading track record a future GTP application will need. Start with our Singapore company incorporation guide or get in touch to discuss your structure.
This guide draws on Enterprise Singapore’s Global Trader Programme guidance and 2026 tax-advisory publications on the GTP 2031 extension and EAC inclusion. Programme terms and eligibility criteria can change — always confirm current requirements with Enterprise Singapore or a tax advisor before applying. Read our editorial and accuracy policy.
No. A standard Pte Ltd can buy, sell, and broker goods internationally from day one. The Global Trader Programme is a tax incentive you apply for separately once you have trading volume and substance — it is not a prerequisite to start trading.
The standard corporate tax rate is 17%. Under the Global Trader Programme, qualifying trading income is taxed at 5%, 10%, or 15% instead, for five years per award — but this requires a separate application and approval from Enterprise Singapore, not automatic eligibility.
It is possible but uncommon. Enterprise Singapore weighs trading track record and volume heavily, so most successful applicants have an established trading history — either built in Singapore over time or brought from an existing overseas trading operation — rather than applying as a day-one startup with no history.
Yes, as of 13 February 2026, Environmental Attribute Certificates (EACs) — including carbon credits and similar tradeable environmental instruments — were added as qualifying “green and sustainable products” under GTP, alongside the programme’s extension to 2031.
Physical trading involves taking ownership of goods as they move through your company; brokering of physical trades involves facilitating a transaction between buyer and seller without necessarily taking title. Both are qualifying activities under GTP, alongside derivative trading in qualifying commodities.
 2 January, 2025
 2 January, 2025
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
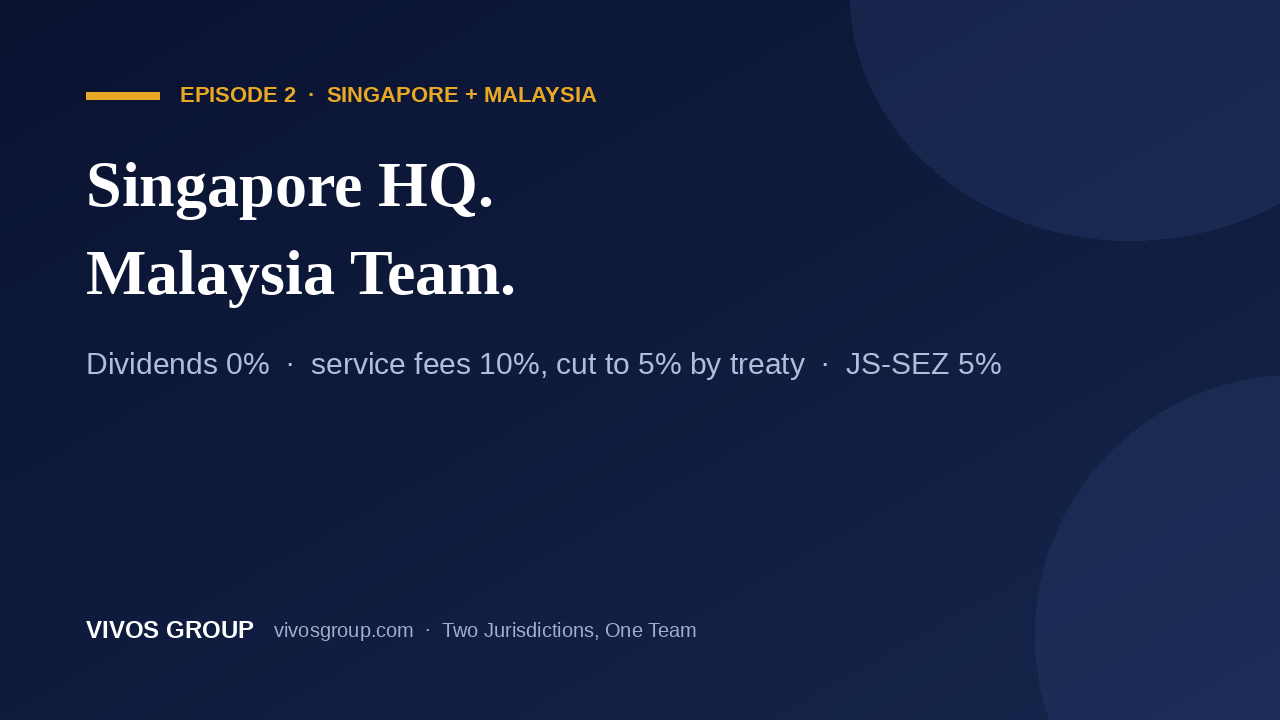
What the Singapore parent of a Malaysian Sdn. Bhd. must get right in 2026: tax-exempt Malaysian dividends under section 13(8), invoicing and 5% treaty withholding,…