Foreign Founders: Skip the Company Seal in Singapore and Sign Remotely

Ray Tay
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
Published: 18 September 2026 · Last reviewed: 30 September 2026 · Reviewed by Ray Tay, Co-Founder & Managing Director, VIVOS PTE. LTD. (ACRA Filing Agent FA20240323 · MOM EA Licence 24S2425)
Quick answer: Singapore has become a genuinely popular relocation destination for UK founders since the UK abolished its non-dom tax regime on 6 April 2025, replacing it with a residence-based system. If you are an individual relocating, the key mechanism to understand is the new 4-Year Foreign Income and Gains (FIG) regime and the Temporary Repatriation Facility. If you are a UK company setting up a Singapore subsidiary instead, the mechanism that matters is the UK’s Controlled Foreign Company (CFC) rules, which can attribute a low-taxed Singapore subsidiary’s profits back to UK tax unless specific exemptions apply. Incorporation in Singapore itself takes 1-3 days regardless of which route applies to you.
TL;DR:
- The UK’s non-dom regime ended on 6 April 2025 — non-UK domicile status no longer determines how foreign income and gains are taxed for UK residents.
- New UK residents who were non-UK-resident for 10+ consecutive years before arriving can claim the 4-Year FIG regime: full UK tax relief on non-UK income and gains for their first four years of UK residence.
- The Temporary Repatriation Facility (TRF) lets individuals bring previously untaxed foreign income/gains into the UK at a reduced rate — 12% in 2025/26 and 2026/27, rising to 15% in 2027/28.
- A UK company setting up a Singapore subsidiary needs to consider CFC rules under Part 9A TIOPA 2010 — these can attribute the Singapore entity’s profits back to UK tax if arrangements exist mainly to reduce UK tax and Singapore’s 17% rate is materially lower than the UK’s.
- A low profits exemption shields most early-stage subsidiaries: CFC rules generally do not bite if the subsidiary’s accounting profits are under £50,000, or under £500,000 with no more than £50,000 of non-trading income.
- VIVOS incorporates the Singapore entity; UK-side personal tax planning (FIG claims, TRF) and CFC analysis are specialist UK tax advisory work done alongside a UK-qualified accountant or tax lawyer.
For decades, “non-dom” status let UK residents whose permanent home was legally elsewhere avoid UK tax on foreign income and gains they did not bring into the UK. That regime ended on 6 April 2025, replaced with a residence-based system that no longer looks at domicile at all. This single change is why Singapore relocation conversations among UK founders and HNW individuals accelerated through 2025 and into 2026 — Singapore’s territorial personal tax system (foreign-sourced income generally untaxed unless remitted, and no capital gains tax) has become the natural comparison point.
The replacement for non-dom status is the 4-Year Foreign Income and Gains (FIG) regime. If you have been non-UK-resident for at least 10 consecutive years before becoming UK-resident again, you can claim full UK tax relief on non-UK income and gains for your first four years of UK residence — a narrower but simpler benefit than the old non-dom remittance basis.
Separately, the Temporary Repatriation Facility (TRF) addresses money that built up offshore under the old regime: individuals can designate previously unremitted foreign income and gains (liquid or illiquid) to be taxed at a reduced rate when brought into the UK — 12% in tax years 2025/26 and 2026/27, rising to 15% in 2027/28. This matters directly for anyone who has been running income through a Singapore structure and is now deciding whether, and when, to bring funds back to the UK.
| Mechanism | What it does | Who qualifies |
|---|---|---|
| 4-Year FIG regime | Full UK tax relief on non-UK income/gains | Non-UK-resident 10+ consecutive years before arrival; first 4 years of UK residence only |
| Temporary Repatriation Facility | Reduced tax rate (12-15%) on bringing old foreign income/gains into the UK | Anyone with previously unremitted foreign income/gains from the pre-2025 non-dom era |
A different regime applies if a UK company — rather than an individual — sets up a Singapore subsidiary. The UK’s Controlled Foreign Company (CFC) rules, in Part 9A of the Taxation (International and Other Provisions) Act 2010, exist to stop UK companies shifting profits into lower-tax subsidiaries purely to cut their UK tax bill.
The practical takeaway: CFC exposure is a real consideration for an established UK company routing meaningful profit through a Singapore subsidiary, but it is not automatically triggered just by incorporating in Singapore — genuine substance and the low profits exemption cover most early-stage situations.
“We incorporate the Pte Ltd, set up the company secretary and accounting, and help you think through what genuine Singapore substance looks like for your business,” says Ray Tay, Co-Founder and Managing Director of VIVOS. “What we do not do is give UK tax advice — whether you qualify for the FIG regime, how to model the Temporary Repatriation Facility, or whether your specific structure clears the CFC gateway test is UK tax law, and it needs a UK-qualified accountant or tax lawyer who knows your full UK position. We work alongside those advisors rather than replacing them.”
VIVOS incorporates the Pte Ltd and keeps your company secretary and accounting compliant while your UK tax advisor handles the FIG, TRF, or CFC analysis on the UK side. Start with our Singapore company incorporation guide or get in touch to discuss your structure.
This guide draws on UK Finance Act non-dom reform provisions effective 6 April 2025, HMRC guidance on the FIG regime and Temporary Repatriation Facility, and Part 9A TIOPA 2010 (CFC rules), cross-checked against 2026 tax-advisory publications. UK tax law is complex and personal circumstances vary significantly — always confirm your position with a UK-qualified tax advisor before relying on any of this. Read our editorial and accuracy policy.
Yes, for new claims — the non-dom remittance basis ended 6 April 2025. It has been replaced by the residence-based 4-Year FIG regime, which is narrower (four years, not indefinite) and requires 10 consecutive years of prior non-UK residence to qualify.
Yes — Singapore’s territorial personal tax system (foreign income generally untaxed unless remitted, no capital gains tax) remains attractive on its own terms. The relevant question is no longer “does UK non-dom status help me” but “does the 4-Year FIG regime apply to me, and does my structure clear UK CFC rules if a company is involved.”
No — CFC rules apply to UK companies controlling foreign subsidiaries, not to individuals. An individual moving to Singapore and setting up a personally-owned Singapore company is a different situation, governed by personal residence and the FIG regime rather than CFC rules.
It is a reduced tax rate (12% in 2025/26 and 2026/27, rising to 15% in 2027/28) for bringing previously untaxed foreign income and gains into the UK. Whether to use it, and when, depends on your full financial picture — this is a UK tax advisory decision, not something to decide from a general guide.
No. CFC rules only bite if profits pass the “gateway test” — broadly, arrangements designed to reduce UK tax with profits increased as a result — and most early-stage subsidiaries are separately covered by the low profits exemption (under £50,000, or under £500,000 with limited non-trading income).
 2 January, 2025
 2 January, 2025
Foreign founders: why a company seal is optional in Singapore since 2017, how Section 41B lets you sign deeds, and practical remote signing workflows.
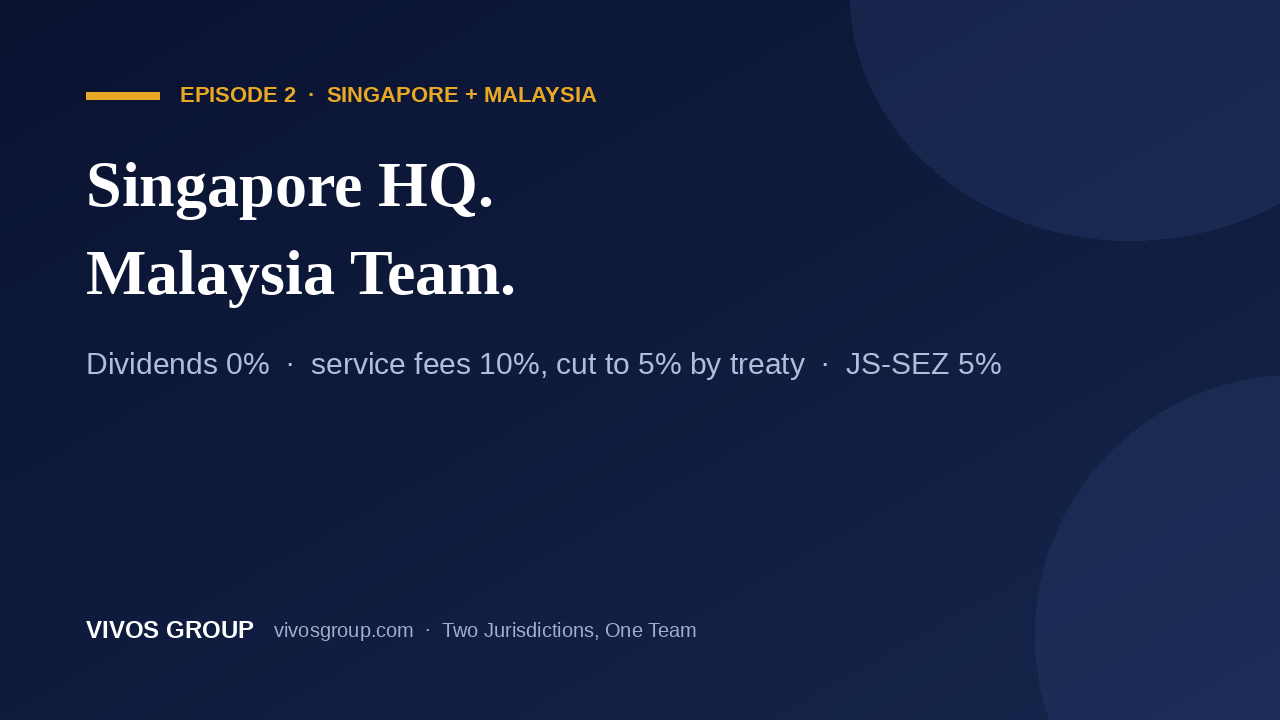
What the Singapore parent of a Malaysian Sdn. Bhd. must get right in 2026: tax-exempt Malaysian dividends under section 13(8), invoicing and 5% treaty withholding,…